Outcome
Activated users in 2 months, up from 12.4K
Increase in loan repayments with partial repayment
Disbursements crossed Rs. 1 crore
Simplifying loans through design.

Team
Product Designer (Me)
2 Product Managers
Product Head
Chief Technology Officer
2 Frontend Developers
2 SDEs
1 QA Tester
My Role
Product Designer ––– Product Architecture, Interaction Design, User Flow, Visual Design,
Prototyping
Overview
FatakEMI is FatakPay's instant loan product, offering up to ₹2,00,000 over 3 to 12 months to blue-collar and gig workers. It's also the product that took FatakPay from B2B to B2C.
Duration
4 months (Dec 2022 - Mar 2023)

When the project landed on my desk, the CTO was crystal clear about the expectations:
1️⃣ Explain EMI plans without financial jargon
2️⃣ Show repayment timelines in an intuitive way
3️⃣ Make trust a visible design feature, with clarity and assurance built right in.
FatakPay's B2B loans were doing well, and lending bigger amounts on EMIs had always been the plan. Once we saw how fast people were adopting the app, it was time.
It was also my first corporate project. I came from mechanical engineering and had never taken an EMI myself. An agency had left a rough first draft, which gave me a place to start.
Where it started
Learning fast
I asked everyone I could about EMIs, from our CA and head of collections to my own parents. A survey through our partner companies got 117 responses. People borrowed for emergencies, medical bills and weddings, and cared most about quick approval and little paperwork.
People borrowed for speed, and cost came second. Some kept taking new loans to repay old ones. That led to two decisions: keep onboarding short and make repayments impossible to miss.
I also studied apps like Slice, Paytm and HDFC PayZapp. Some blocked screenshots, so my PM filmed my phone while I went through their flows.
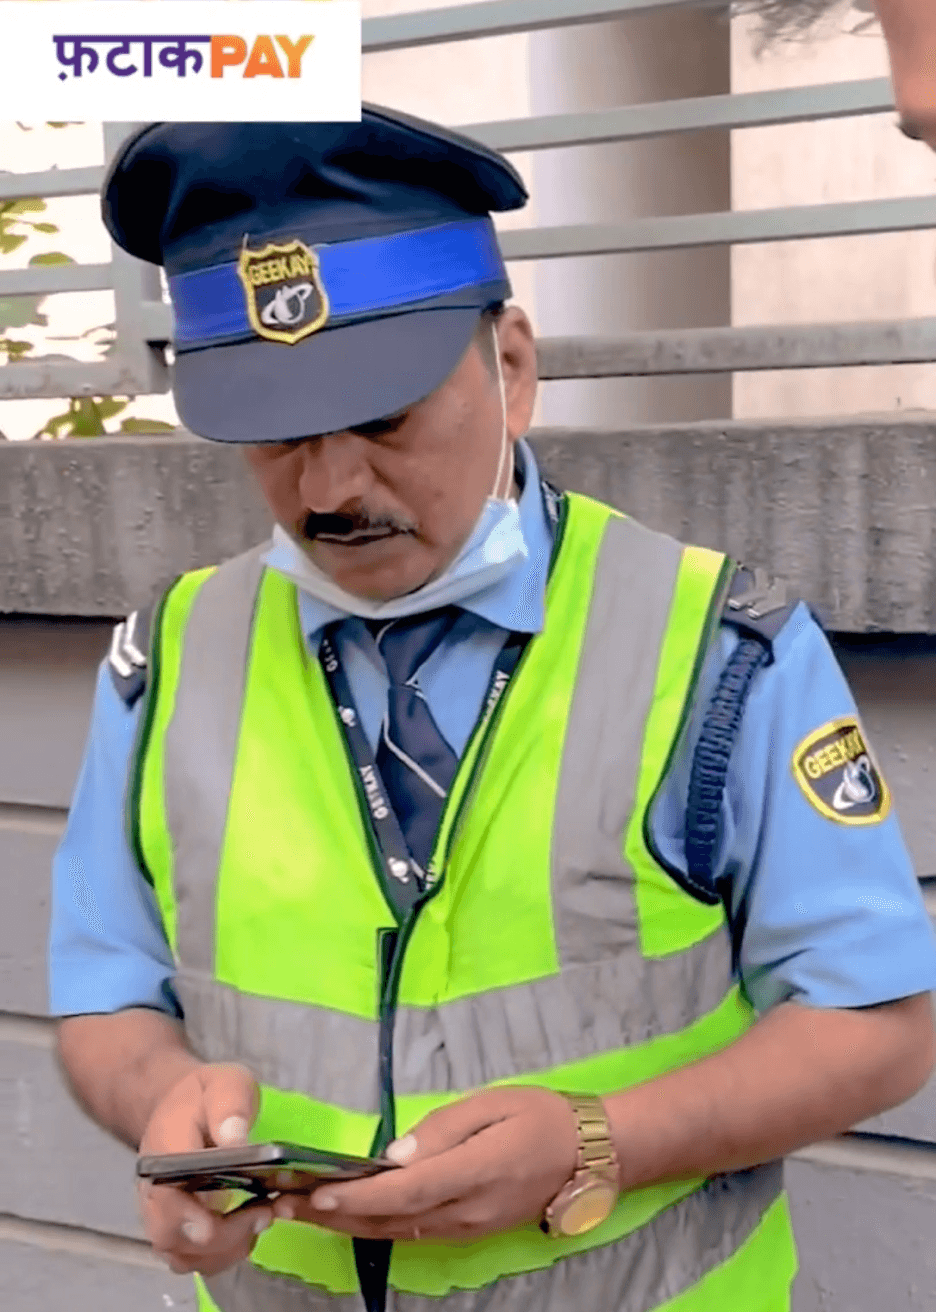
But those respondents were mostly comfortable with tech, unlike our real users. So I started chatting with the security guards and janitors in our co-working space.


Fitting EMI into the existing flow
For the pilot, FatakEMI was offered only to existing FatakCredit users. Their KYC was already stored, so they confirmed it, checked their offer, picked an amount and tenure, and set up auto-debit. Bigger loans meant more risk, so we also asked for 3 months of bank statements.

Challenge: partial repayments
During pilot testing, we discovered an issue. Some users were paying partial EMIs, but the system only marked instalments as cleared if fully paid. Holding partial amounts internally was risky due to RBI regulations only allowing wallets feature to store money, and licensing one wasn’t viable.
Workaround and design update
To solve this, I introduced a new signifier: Yellow, representing partial repayment.
▫️ The “Total Due Amount” field became clickable, revealing the detailed breakup: partial carry-forward + current EMI.
▫️ Scheduler blocks also reflected partial amounts with the new yellow icon.
▫️ This approach not only solved the compliance issue but also gave users visibility into penalty fees for delayed or missed payments.
Witnessing the impact
Once released, the update was a success. Total disbursement crossed Rs. 30 Lakhs in just 2 weeks, with sharp growth in app installations and onboarding from partner corporates. Energised by this momentum, stakeholders expanded the vision from a corporate-only product to a B2C offering.
Designing the EMI Dashboard
Pay Now
EMI Schedule
Total Due
₹ 3,136.42
₹ 25,000.00
Loan Outstanding
06 Oct 2023
EMI Due Date
30%
ROI (p.a.)
20 Months
Tenure
EMIs Paid : 10
10/20
Overdue EMIs : 4

Inspiration and solution for EMI status
The breakthrough came unexpectedly. While making a payment on a food delivery app, my failed transaction was signalled with a bold red icon and text. This reminded me of how universal traffic-light colours are in shaping human behaviour. I applied the same principle:
▫️ Green check circle for successful EMI repayment
▫️ Red cross circle for defaults (missed EMI)
▫️ For 12-month loans, a progress bar replaced individual icons for scalability
The scheduler was designed as sequential blocks, each showing: Due Date, Principal, Interest, Instalment Amount, and Status Signifier. This made monthly obligations transparent at a glance.
FatakPay limited EMI tenures to 3, 6, 9, and 12 months. The stakeholders wanted to reuse our signature card design, so I adapted it for this product. The card now displayed only essential fields:
Total Due Amount
Due Date
Loan Outstanding Amount
Rate of Interest (ROI)
Tenure
Clarity here was critical to building trust and avoiding ambiguity. Unlike competitors with 10-year loan visualisations, we focused on shorter terms that demanded simple, intuitive displays.
Fig. 5.1. The EMI version of the epic card
Most EMI apps are made for white-collar users. Ours needed everything spelled out.

Fig.5.4. Partial repayment feature designed for flexibility in loan management
Going B2C meant users shouldn't have to finish onboarding for one product before seeing the other. We cut onboarding to name, phone, income type and a selfie. Everyone then lands on a Unified Home with both loans, credit score checks, insurance and investments. Even people who got rejected had something useful to do.
Two products, one home
It went live in March 2023. Downloads reached 4.3K within weeks and some borrowers exploited gaps, so we made location sharing mandatory and opened region by region.
Despite the rocky start, the EMI product under this unified B2C model went on to cross Rs. 1 crore in disbursements, proving the remodel’s long-term impact.


Working on FatakPay was more than just a design role. It was my first real immersion into a high-pressure startup environment where design decisions had a direct impact on growth, compliance, and trust. From redesigning onboarding for underserved users to shaping an entirely new product ecosystem, every challenge pushed me to think beyond visuals and focus on business impact.
What was achieved
✅ Transformed the onboarding journey into something accessible for a largely blue-collar audience.
✅ Created scalable design systems that adapted to regulatory shifts and product pivots.
✅ Helped unify two loan products under a single experience, leading to rapid adoption and over Rs. 1 crore in disbursements.
✅ Designed features that gave users more control and transparency, building trust in a sensitive financial domain.
Impact, Learnings, and the Road Ahead
Design in fintech isn’t just about usability; it’s about responsibility. Every interaction must balance user ease, compliance, and company risk.
When formal research got blocked, talking to the guards in my building filled the gaps.
Next time, I'd set up analytics from day one and plan for scale before launch.
What I learnt